The GSIS solar loan, officially the Ginhawa Solar Energy Loan (GSEL), lends up to ₱500,000 (up to 100% of your system's cost) at 5% a year "computed in advance", paid over 60 equal monthly installments. On a ₱500,000 loan, GSIS's own figure is ₱10,416.67 a month. Active members need at least 3 years in government service, and since 30 September 2026 pensioners up to 80 years old can apply too. Everything goes through the GSIS Touch app, and you upload just one document: a quote, a signed contract or an official receipt.
Kung teacher ka, nasa LGU ka, or retired government worker in Leyte or Biliran, this may be the cheapest solar loan you can get right now. But the "5%" doesn't work like a bank's 5%, and a couple of rules can catch you out. Here's what the GSIS papers say, with the maths worked out.
Last checked 2 November 2026, from the GSIS GSEL pages, the GSIS FAQ and GSIS Memorandum Circular No. 075, s. 2026. Rules can change, so confirm in GSIS Touch before you sign anything.
GSEL at a glance
Term | What GSIS says |
|---|---|
Maximum loan | ₱500,000, up to 100% of the cost of panels, equipment and installation |
Cap | Never more than the cost shown on your quote, contract or receipt |
Term | 5 years, 60 equal monthly installments |
Interest | 5% a year, computed in advance (effective rate 9.54835% a year) |
Monthly payment on ₱500,000 | ₱10,416.67 |
Service fee | None |
Deducted from what you receive | Interest in advance (part-month) and a one-time loan redemption insurance premium |
Free insurance on the system | 3 years, against earthquake, fire/lightning and typhoon |
Paying early | Allowed, no pre-termination fee |
Cancelling | Within 30 calendar days of loan granting |
How to apply | GSIS Touch app only; no walk-in or manual applications |
Sources: GSIS GSEL page and FAQ; GSIS MC 075, s. 2026 (links at the end).
Who can apply
Active government workers
From the GSIS circular and its GSEL page, you qualify if you're an active member (permanent or non-career status, including special members) and:
- you've been in the service for at least 3 years;
- you've paid at least one month of personal and government share premiums in the last 6 months;
- you have no pending administrative case or criminal charge, and you're not on leave without pay;
- you have no GSIS loan in default (a housing loan is the exception);
- your agency isn't tagged "suspended" in GSIS records; and
- your net take-home pay after the loan stays at or above the floor. The GSIS FAQ puts that at ₱5,000.
Your Agency Authorized Officer (AAO) must certify the application online within 7 calendar days, or it's cancelled. Give your HR office a heads-up after you file.
Pensioners (since 30 September 2026)
GSIS opened GSEL to pensioners on 30 September 2026. Its pensioner page says you qualify if you're an old-age pensioner (regular, disability or portability) and:
- you were not more than 80 years old on your last birthday;
- you've been receiving a monthly pension for at least one month; and
- you have no outstanding loan being paid under CLASP (the Choice of Loan Amortization Schedule for Pensioners) or a restructuring program.
There's also a pension floor: after GSEL and other pension-loan deductions, your net monthly pension should generally stay at least 25% of your basic monthly pension. If it would drop below that, the loan can go ahead only with your explicit agreement. And if your pension is suspended because you missed your APIR (annual revalidation), the GSEL deductions pause too, with no penalty; the missed payments come out of your pension once you comply.
Requirements: what to upload in GSIS Touch
You upload any one of these when you apply:
- Solar proposal or quote from an installer, showing the system cost, installation fees and equipment;
- Signed installation agreement or contract, with the terms and warranties; or
- Official receipt, if you already paid and want reimbursement. This only works for systems installed in 2026 onwards.
Whatever you upload sets your maximum: GSIS won't lend more than the cost on that document. So ask for an itemised quote with model numbers. Our solar contract checklist and how to choose an installer cover what a good one includes.
After installation, don't forget this. The circular says you must notify GSIS within 6 months of loan release with a certification from the service provider, photos of the finished installation and one of the documents above. GSIS has a "Submission of Proof of Completion" form on its GSEL page. If you miss the deadline, GSIS treats it as no installation, and the whole loan becomes due at once. The free 3-year insurance also only starts after you submit this notice and GSIS issues the policy. (The pensioner page doesn't repeat this rule, so pensioners should confirm it in GSIS Touch.)
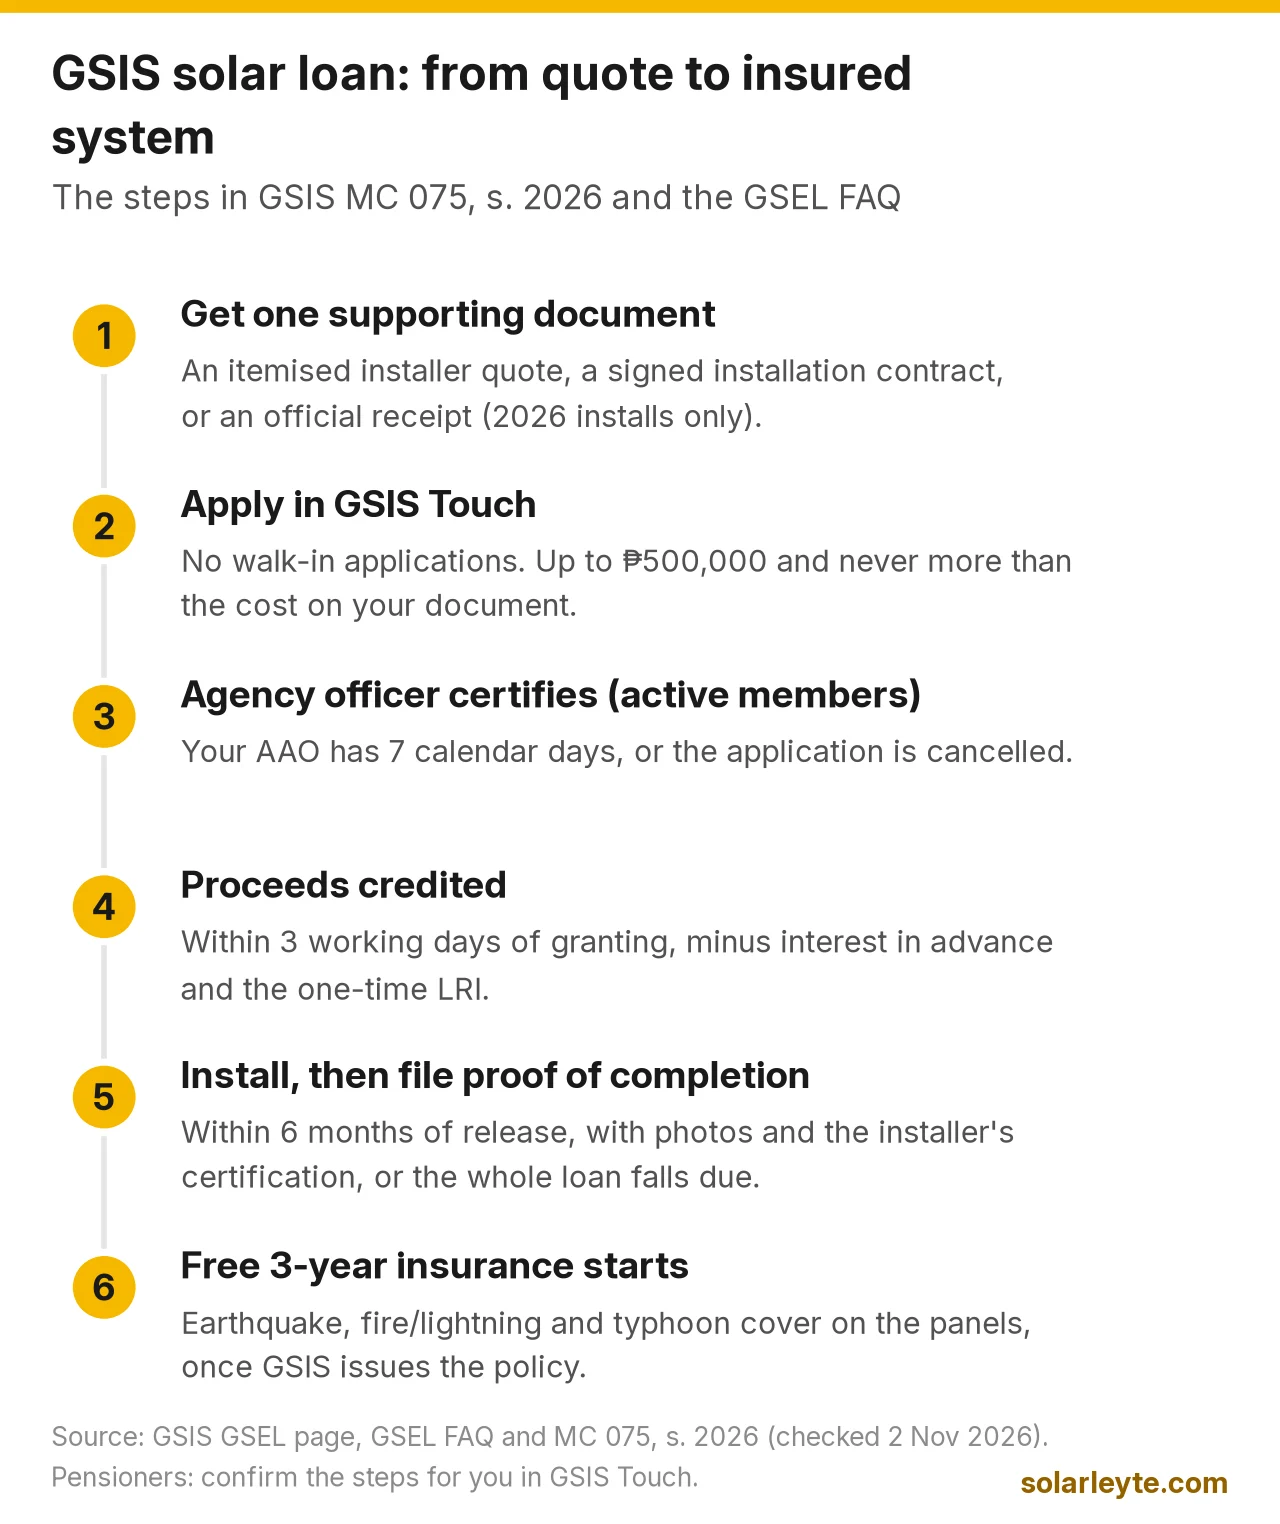
GSIS solar loan computation, step by step
The monthly payment
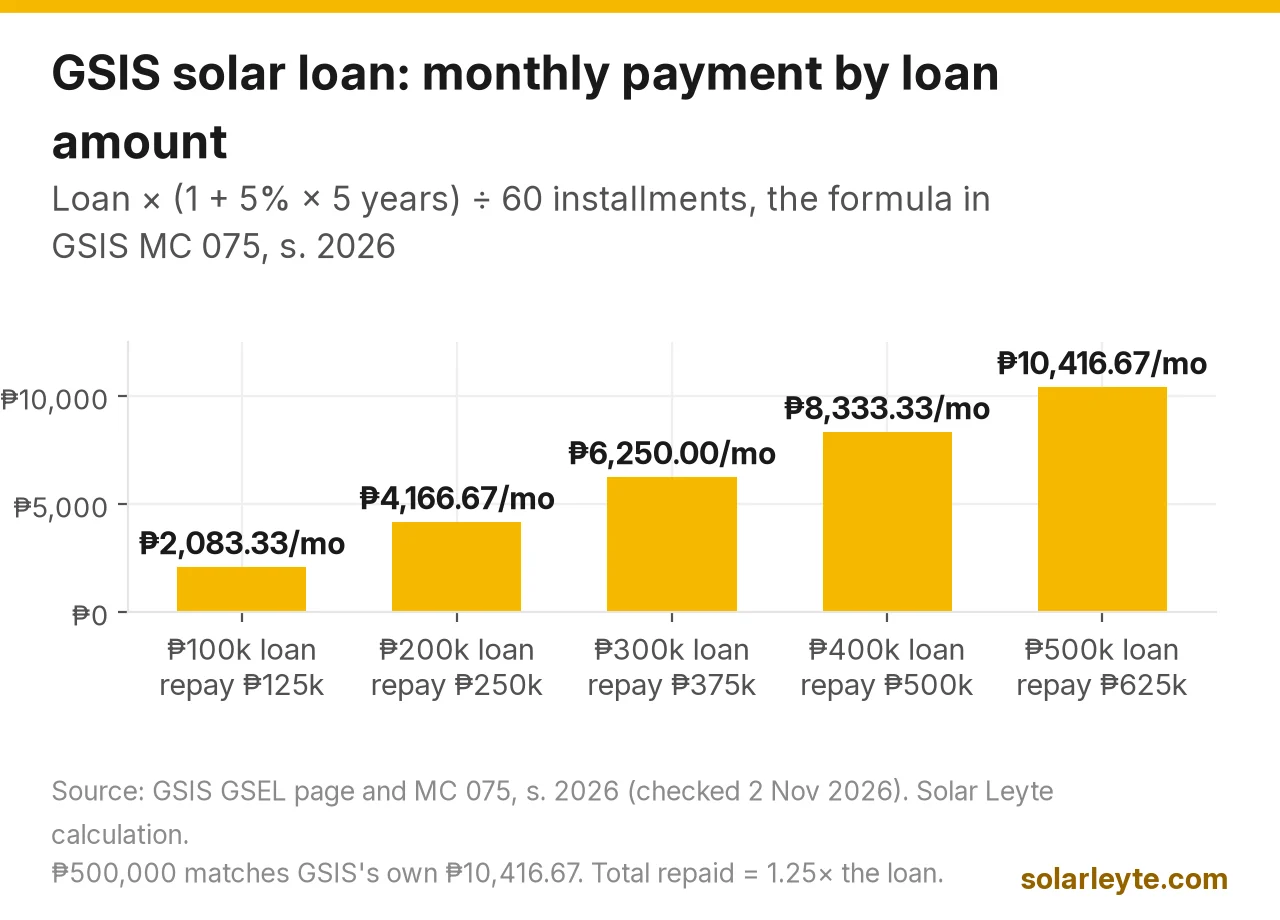
GSIS uses an add-on formula: loan × (1 + 5% × 5 years) ÷ 60. You pay interest on the full amount for all five years, even as the balance goes down. That's why GSIS states the effective rate as 9.54835% a year. (We checked: a flat ₱10,416.67 for 60 months on ₱500,000 works out to exactly that rate, compounded monthly.)
Loan amount | Monthly payment | Total paid over 5 years | Total interest |
|---|---|---|---|
₱100,000 | ₱2,083.33 | ₱125,000 | ₱25,000 |
₱200,000 | ₱4,166.67 | ₱250,000 | ₱50,000 |
₱300,000 | ₱6,250.00 | ₱375,000 | ₱75,000 |
₱400,000 | ₱8,333.33 | ₱500,000 | ₱100,000 |
₱500,000 | ₱10,416.67 | ₱625,000 | ₱125,000 |
Solar Leyte calculation using the formula in GSIS MC 075, s. 2026. The ₱500,000 row matches GSIS's own figure.
Some online calculators show about ₱9,436 a month for ₱500,000. That's what a standard 5% declining-balance loan would cost, but it isn't how GSEL is computed. Use GSIS's ₱10,416.67.
What actually lands in your bank account
Two things come off the loan before it's credited:
- Interest in advance (IDA): a part-month of interest, from the day the loan is granted to the end of the month before your first due month. Formula: loan × 9.54835% × days ÷ 360.
- Loan redemption insurance (LRI): a one-time premium of ₱19.70711 per ₱1,000 borrowed in the circular's table. GSIS says that if the borrower dies, the loan may be considered settled.
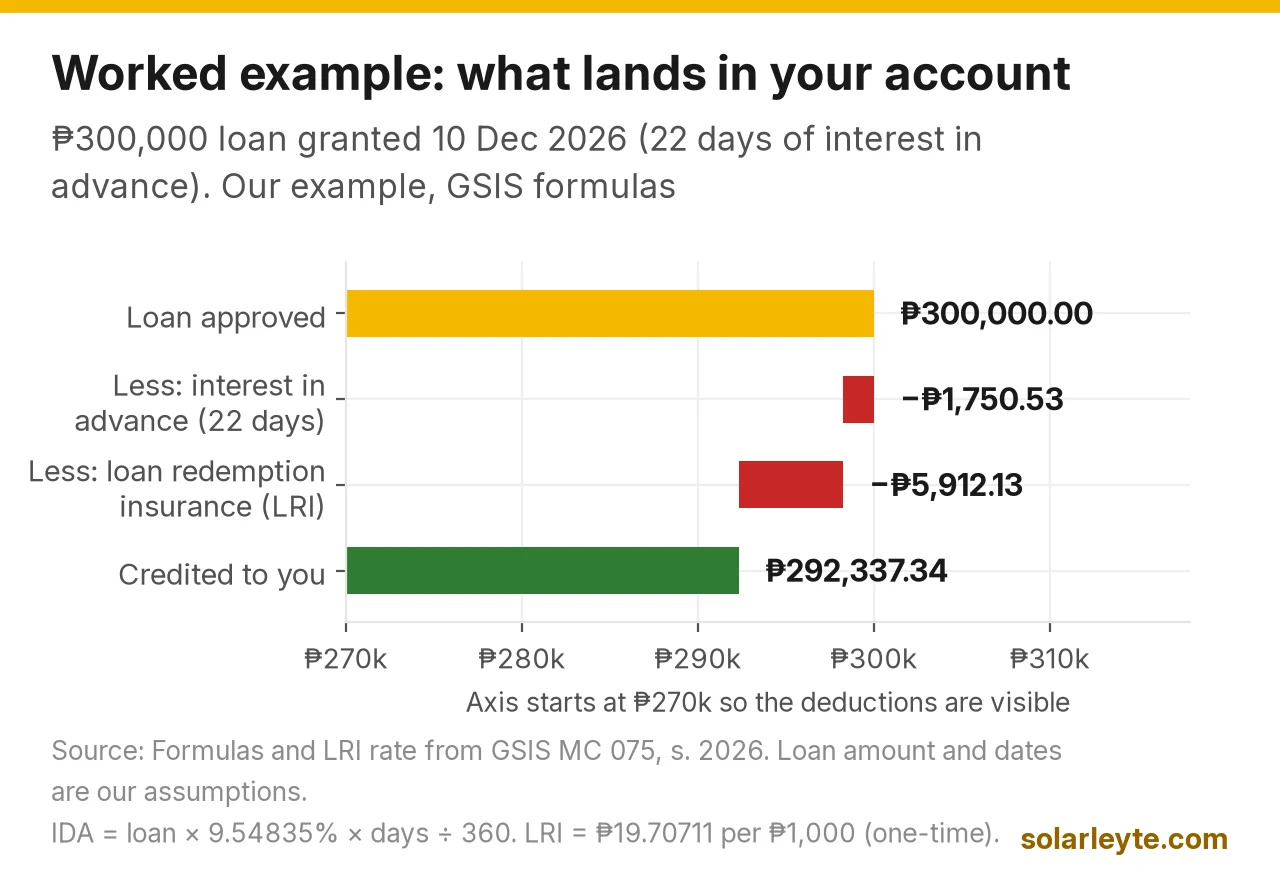
Worked example A (active employee, our assumptions): a teacher borrows ₱300,000 for a quoted system. The loan is granted on 10 December 2026. Because that's on or before the 23rd, the first due month is January 2027, so the IDA covers 22 days (10 to 31 December).
- IDA: ₱300,000 × 9.54835% × 22 ÷ 360 = ₱1,750.53
- LRI: 300 × ₱19.70711 = ₱5,912.13
- Credited to the account: ₱300,000 − ₱1,750.53 − ₱5,912.13 = ₱292,337.34
- Monthly payment by salary deduction: ₱6,250.00 for 60 months (₱375,000 in total)
- Take-home pay check: if take-home is ₱15,000 before the loan, it's ₱8,750 after, which clears the ₱5,000 floor. At ₱15,000, the most you could add is ₱10,000 a month, about a ₱480,000 loan.
The dates, take-home pay and loan amount are our assumptions. The formulas and the ₱19.70711 rate are from the circular, which reviews the LRI rate every year. GSIS says proceeds are credited within 3 working days of loan granting.
So budget for the gap: on a ₱300,000 quote you receive about ₱7,700 less, which you cover yourself.
Worked example B (pensioner, our assumptions): a retired nurse in Naval has a basic monthly pension of ₱12,000 and no other pension loans. To keep 25% (₱3,000), her GSEL payment can go up to ₱9,000 a month, which is about a ₱432,000 loan (₱9,000 × 60 ÷ 1.25). The full ₱500,000 at ₱10,416.67 would leave her ₱1,583.33 a month. That's possible only with her explicit agreement, and it's probably not wise. GSIS doesn't publish a separate pensioner LRI rate on its page, so check the net proceeds shown in GSIS Touch before you confirm.
Late payments, retiring and paying early
- Late payments: penalty interest of 1% a month plus a 0.5% a month surcharge on unpaid installments. Even one day late counts as a full month. The loan is in default once more than 6 monthly installments are unpaid, and then the whole balance becomes due.
- If you resign or retire: the loan is pre-terminated and GSIS collects the balance from your claims. The circular gives retirees an option to move it to CLASP.
- Paying early: allowed, with no fee.
- Cancelling: within 30 calendar days of granting, by repaying the principal plus pro-rata interest.
GSEL vs the other ways to pay
GSEL isn't your only option:
Option | Who it's for | Read more |
|---|---|---|
GSIS GSEL | Active GSIS members with 3+ years' service; pensioners up to 80 | This post |
Pag-IBIG home improvement loan | Pag-IBIG members who own the house | |
SSS solar loan | Private-sector members, once it opens | |
Bank solar and home loans | Anyone a bank approves | |
Rent-to-own or installer plans | People who can't or won't borrow |
For the bigger picture, see our guide to paying for solar. To check whether the bill savings can cover the payment, see is solar worth it in Leyte and Biliran.
FAQ
Can I use the GSIS solar loan for a system I already installed?
Yes, if it was installed in 2026 or later. Upload the official receipt as your supporting document. GSIS won't lend more than the amount on the receipt.
Does GSIS have a list of accredited solar installers?
We didn't find one on the GSIS GSEL pages. The circular only asks for a quote, contract or receipt from "a solar panel installer", and a completion certificate from the "authorized service provider". Ask GSIS if you're unsure whether your installer's paperwork will be accepted.
Is there fire insurance on the panels?
Yes. GSIS covers the panels free for the first 3 years against earthquake, fire/lightning and typhoon, while the loan is active. It starts once the GSIS policy is issued after your completion notice, and GSIS's page has a consent form for it. Coverage above the loan amount, or after year 3, is up to you. See our solar insurance guide.
Can I sell extra power to BILECO or LEYECO?
The GSIS FAQ (Q38) says members can sell excess electricity back to the grid under net metering. In practice, exported power earns peso credits on your electric bill, not cash payments. Those credits are valued at the utility's blended generation cost (ERC Res. 15 s.2025) and roll over. That's a separate application with your co-op (e.g. BILECO, LEYECO), not part of the loan. Our net metering guide explains the steps.
How long does approval take?
GSIS doesn't publish a total. Your AAO has 7 calendar days to certify (active members), and GSIS says approved proceeds are credited within 3 working days of granting.
Solar Leyte is run by MACC Systems & Energy Solutions Inc., a solar installer in Naval, Biliran. We aren't affiliated with GSIS and can't approve loans.
Get a free solar quote from MACC
Applying for GSEL? You'll need an itemised quote first. Send us a photo of your latest BILECO or LEYECO bill and we'll reply with options and a written quote you can upload in GSIS Touch. No obligation.
- Call/Text: 0955 723 5093
- Email: official@macc-inc.com
- Website: www.macc-inc.com
Sources (all checked 2 November 2026)
- GSIS, Ginhawa Solar Energy Loan page: qualified borrowers, 5% computed in advance, one supporting document via GSIS Touch, AAO certification, LRI, monthly amortization formula and ₱10,416.67 on ₱500,000, up to 100% of cost and ₱500,000 maximum, 60 equal installments, no pre-termination fee, 30-day cancellation, proof-of-completion and fire-insurance consent forms.
- GSIS, GSEL for Pensioners page: old-age (regular, disability, portability) pensioners not over 80 on last birthday, at least one month of pension, no outstanding CLASP or restructuring loan, 25% of basic monthly pension rule, APIR suspension rule, same rate, amount and term.
- GSIS, GSEL Frequently Asked Questions (PDF, Filipino and English): no service fee, NTHP minimum ₱5,000, GSIS Touch only, reimbursement for 2026 installs, AAO 7 days, proceeds within 3 working days, 3-year insurance (earthquake, fire/lightning, typhoon), 6-month completion notice, default after 6 months, initial program period 3 years, net metering answer (Q38).
- Ocampo & Suralvo on ERC Resolution No. 15, s. 2025: net-metering exports credited as peso bill credits at the utility's blended generation cost (excluding other generation adjustments); unused credits bank and roll over.
- GSIS Memorandum Circular No. 075, s. 2026, as attached to NIA Memorandum Circular 2026-047 (PDF): full guidelines, including effective rate 9.54835%, IDA formula and samples, LRI rate 19.70711 per ₱1,000, net proceeds, due-month rules (23rd cut-off), penalties 1% + 0.5% a month, 6-month completion rule, insurance, compulsory pre-termination and CLASP option.
- GSIS press release, 23 September 2026: GSEL for pensioners from 30 September 2026; launched for active members in March 2026.
- Philstar, "GSIS solar loans now available to pensioners", 2 October 2026 and Daily Tribune, 29 September 2026: pensioner launch, up to ₱500,000, five years, 5%, no service fee, GSIS Touch.
- PIA Caraga, 15 October 2026: GSIS Butuan branch on pensioner eligibility (regular old-age up to 80, disability, Portability Law).
- Worked examples, the loan-amount table, the effective-rate check and the ₱9,436 comparison: Solar Leyte calculations from the formulas above.